Medicare, taught before it's sold.
Turning 65, still working, or reviewing this year's plan, we start by making sure you understand the parts, the paths, and the deadlines. Then we compare real options together.
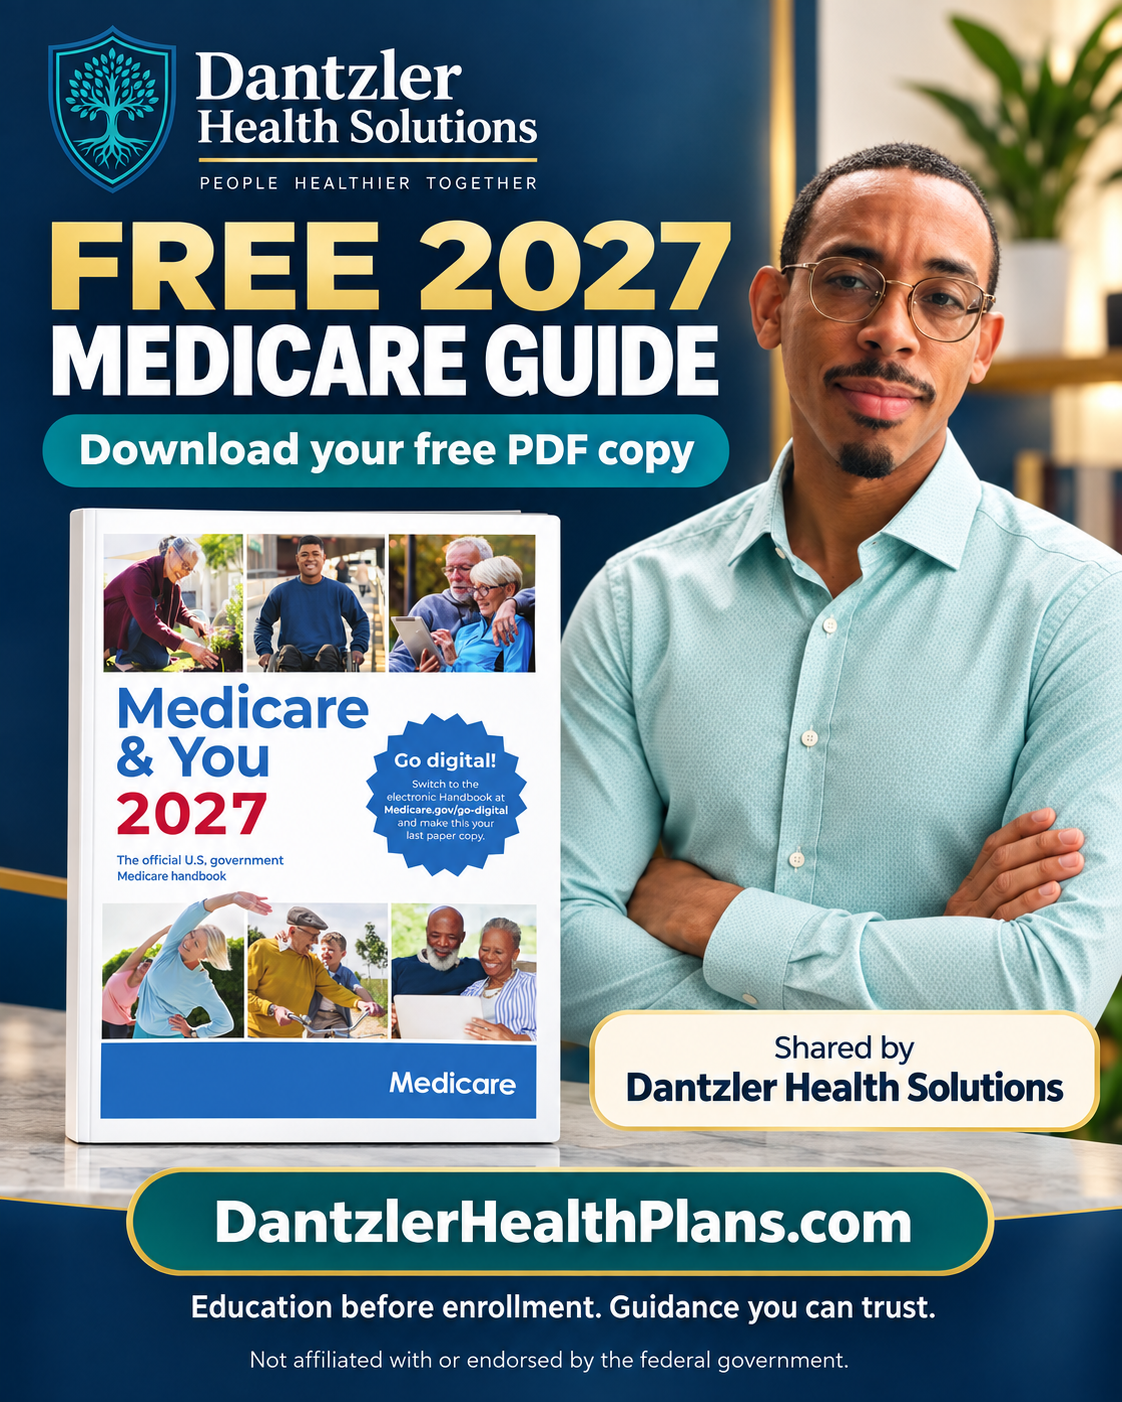
Medicare & You 2027
Read the official Medicare handbook covering Medicare benefits, coverage choices, drug coverage, cost-assistance programs, rights and protections.
The four parts, in plain English.
Hospital insurance
Inpatient hospital stays, skilled nursing, hospice, and some home health care.
Medical insurance
Doctor visits, outpatient care, preventive services, and durable medical equipment.
Medicare Advantage
A private plan that bundles A and B, often with Part D and extras, usually through a network. Benefits depend on the plan.
Prescription drugs
Standalone drug coverage. Each plan has its own formulary and pharmacy network.
Advantage or Supplement, with the trade-offs shown.
We won't pretend one is right for everyone. Here's the honest version of each.
Medicare Advantage (Part C)
- May have a lower or $0 monthly premium, depending on the plan
- May include extras like dental, vision, hearing, or fitness
- Includes a yearly out-of-pocket maximum for covered Part A and B services
Medicare Supplement (Medigap)
- Generally lets you see any U.S. provider that accepts Medicare
- Out-of-pocket costs are often more predictable, depending on the plan
- Usually no referrals; travel coverage depends on the plan
Part D Prescription Plans
- Covers medications on the plan's formulary
- Enrolling when first eligible may help you avoid late-enrollment penalties
- Reviewed annually as formularies change
When you can enroll or change plans.
Initial Enrollment Period
Your first window. Enrolling on time may help you avoid lifelong penalties.
Annual Enrollment Period
Change Advantage or Part D plans for coverage starting January 1.
Medicare Advantage Open Enrollment
Already in an Advantage plan? You get one switch or a return to Original Medicare.
Special Enrollment Periods
Moving, losing employer coverage, or plan changes can open a window any time of year.
Answers before appointments.
Talk to a licensed agent.
Bring your doctors and your prescription list. We'll do the rest.